A candidate stood at a mosque pulpit during Ramadan and asked worshipers to help put his name on the ballot.
Story Snapshot
- Federal tax law bans tax-exempt charities, including mosques, from backing candidates.
- Guidance lists endorsements, solicitations, and use of facilities for campaigns as red flags.
- A report says Abdul El-Sayed sought signatures at a Michigan mosque and received a pulpit boost.
- The dispute fits a long-running pattern where rules are clear but enforcement is rare.
What reportedly happened inside Michigan mosques
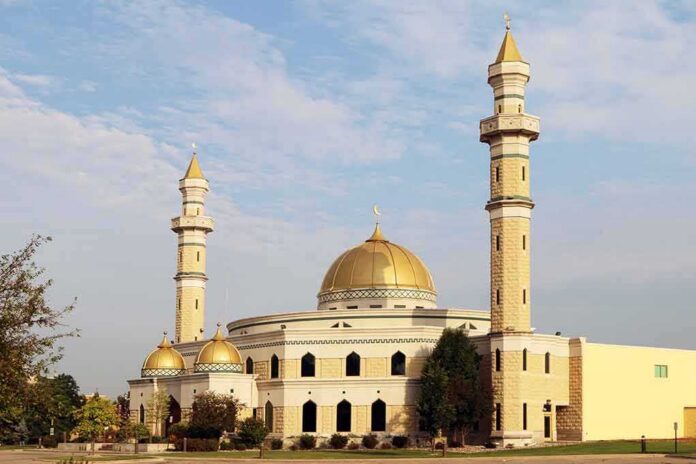
The Middle East Forum reported that Abdul El-Sayed spoke from the pulpit at the Islamic House of Wisdom in Dearborn Heights during a Ramadan prayer service. The report says he asked congregants to sign his nominating petitions for the Michigan Democratic primary. It also quotes Imam Mohammad Ali Elahi urging the audience to vote for El-Sayed. The write-up highlights specific names, a venue, and action tied to an election event, which raises legal questions under federal charity rules.
American Association of Mature Citizens coverage adds that El-Sayed courted several Muslim centers. It describes clerics at some sites using harsh political language, and it notes the same allegation about in-mosque petition gathering. That piece frames the activity as political in nature and points to sermons that mixed religious themes with calls related to the election season. Its core contribution is the on-site petition claim and the asserted pulpit endorsement.
What the law says charities and houses of worship can and cannot do
The Internal Revenue Service states that all section 501(c)(3) organizations are absolutely barred from taking part in any political campaign for or against a candidate. That rule applies to churches, synagogues, and mosques alike. The agency explains that endorsements, soliciting contributions, using staff or space for campaign work, or distributing material that backs a candidate can count as intervention. The restriction covers federal, state, and local races, including primaries.
Internal Revenue Service training material gives examples that help draw the line. Leaders of a charity cannot use official events or organizational resources to support a candidate. The agency flags inviting one candidate to speak while denying equal access to others, or letting campaign activity occur at a service, as potential violations. It warns that statements by organizational representatives can be attributed to the charity if made in an official setting, like a pulpit, newsletter, or website.
How these facts line up with the rule
The reported scene involves three elements the Internal Revenue Service treats as relevant: a candidate’s solicitation, an apparent religious-service setting, and a leader’s express vote message. If a tax-exempt religious organization hosted that activity during worship and used institutional standing to urge votes, the conduct tracks examples of campaign intervention. That does not declare anyone guilty of a violation; it explains why the events, as described, warrant scrutiny under a clear legal standard.
Common-sense guardrails apply. Equal access for all candidates, clear neutrality notices, and a strict ban on fundraising or petitioning during services can keep a charity within the law. When a candidate appears, the organization must avoid any sign of support or opposition. Allowing signature collection on-site or having an imam declare a voting choice from the pulpit cuts against that neutral posture and fits the Internal Revenue Service’s warning examples.
Why this matters beyond one event
America asks charities to pick a lane: stay out of electioneering in exchange for a tax break. That bargain protects faith from being turned into a campaign machine and protects taxpayers from subsidizing partisan drives. The pattern is old and crosses faith lines. The Internal Revenue Service has long said the rule is firm, yet follow-through is uneven. That gap invites repeat tests of the boundary and erodes trust that the standard applies to everyone the same way.
The practical next steps that align with rule-of-law values
Responsible review starts with documents and dates. Verify each institution’s tax-exempt status. Check calendars, service videos, and facility-use policies. Ask whether other candidates were offered the same access. Separate private speech outside services from pulpit use during worship. If a tax-exempt organization enabled petitioning or endorsements in an official setting, the Internal Revenue Service has a textbook case to examine. The country does not need censorship; it needs evenhanded enforcement of clear, neutral rules.
Sources:
© partiallypolitics.com 2026. All rights reserved.